fo / en

Category: News

  • Market update for september 2026

    Market update for september 2026

    What happened in September?

    Global equities rose by 1% in September, bringing the total return over the past 12 months to 17%. The positive performance in September was driven primarily by a handful of large US stocks, especially technology stocks related to artificial intelligence (AI). A stronger US dollar also contributed to the positive returns.

    Danish equities fell by as much as 4.6% in September, mainly due to another decline in Novo Nordisk. Nordic equities also had a poor month, with a return of -3.9%. Overall, many stock markets around the world fell in September.

    Oil prices and interest rates rose further in September. This resulted in negative returns across all types of bonds, a flatter yield curve, and lower prices for precious metals such as gold and silver.

    Danish short-term and long-term bonds delivered negative returns of -0.4% and -1.5%, respectively. Corporate bonds and bonds from high-yield markets also recorded negative returns of -1.5% and as much as -4%, respectively.

    Why? Optimism about AI is temporarily offsetting higher inflation and interest rates

    Global investor optimism, driven particularly by large investments in AI, continued in September. This strengthened earnings expectations for AI companies and temporarily offset the negative impact that substantial interest rate increases had on many AI and technology stocks.

    On the other hand, substantial borrowing needs among governments and technology companies, continued global economic growth, and growing uncertainty about inflation have pushed interest rates higher. The uncertainty surrounding inflation stems, among other things, from the ongoing conflict in the Middle East.

    Higher interest rates have hit bond markets hard and have also negatively affected several stocks outside the technology sector, including bank stocks and shares in companies that sell consumer goods.

    High interest rates and a flattening yield curve—when short-term interest rates rise more than long-term rates—can make it more difficult for these companies to operate profitably.

    Global growth continues, but several challenges lie ahead

    As we enter the fourth quarter, global economic growth continues. The latest surveys of business conditions in Europe, the United States and Asia certainly point in that direction. They all indicate solid growth across several industries.

    US labour market figures and reports from the global technology sector also suggest that favourable conditions for growth and profitability are likely to persist for some time.

    However, there is a downside: companies are simultaneously reporting increasing price pressures. Input costs are rising, and companies expect to pass these price increases on to consumers over the coming months.

    The global economy is therefore experiencing strong growth, but inflation is also increasing. As a result, several central banks are still raising interest rates to prevent inflation from becoming excessive.

    Rising interest rates are also creating turbulence in financial markets because borrowing money and servicing debt are becoming more expensive. This is expected to slow economic growth over the coming quarters.

    At the same time, renewed concerns have emerged about France within the eurozone. The country is struggling with a large budget deficit, rapidly rising government debt and political disagreements over how to resolve its debt problems.

    In the short term—that is, over the coming weeks and months—financial markets will be paying particular attention to third-quarter earnings reports, developments in the war in Iran, trade negotiations between the EU and China, and concerns about debt levels in the eurozone.

    Looking further ahead, the key question will be whether growth in AI is sustainable. This will have a major impact on whether global economic growth and the positive trend in equity markets can continue.

    Several industries—not just the technology sector—are benefiting during this period from substantial investments in computer equipment, data centres and other technological infrastructure.
  • Rune Nørregaard will become the new CEO of LÍV

    Rune Nørregaard will become the new CEO of LÍV

    The boards of P/F Tryggingarfelagið LÍV and P/F LÍV Lívs- og pensjónstryggingarfelag have appointed Rune Nørregaard as the new CEO of the LÍV Group. In connection with the appointment, Annbritt Tummasdóttir Andersen from Momentum Consulting has served as an external adviser to the boards and led the recruitment and assessment process. Rune will take up the position at a later date by mutual agreement.

    As CEO, Rune Nørregaard will lead the development of LÍV, with particular emphasis on strengthening operations, achieving strong and stable results, and establishing a clear strategic direction for the group.

    “Rune has extensive leadership experience and in-depth knowledge of the banking, insurance and pension sectors. I know him as a highly capable and results-driven leader who is able to combine strategic oversight with sound operations and clear leadership. He knows Faroese society and the business community well, and the boards are convinced that he is the right person to lead the continued development of LÍV,” says Árni H. Ellefsen, Chairman of the Board of P/F Tryggingarfelagið LÍV.

    Rune Nørregaard has more than 15 years of experience in the financial and insurance industries in Denmark, the Faroe Islands and the other Nordic countries. He is currently CEO and Chief Operating Officer (COO) of kompasbank, where he serves on the executive management team together with the founder and is responsible for, among other things, operations, sales and credit.

    Before joining kompasbank, Rune Nørregaard worked for 13 years within the Føroya Banki Group. For 12 of those years, he was part of the group’s executive management, serving in roles including Chief Credit Officer and Chief Financial Officer. He was responsible for finance and analysis, treasury, credit, IT, and several other important operational and support functions.

    In connection with the Faroese pension reform, Rune Nørregaard was responsible for establishing the life insurance company NordikLív, and he became the company’s first CEO. He also has board experience from the insurance companies Trygd and Vörður and has previously been approved to lead both life and non-life insurance companies.

    Rune Nørregaard holds a Master of Laws (cand.jur.) degree from Aarhus University and also has a Global Executive MBA from IE Business School. He has additionally completed the board education programme for board members of insurance and pension companies at Forsikringsakademiet. In addition, he has worked as a Senior Legal Advisor at Danske Bank and as an attorney at Bech-Bruun.

    “LÍV manages a large share of the pension savings of the Faroese workforce and therefore has a special responsibility towards its customers, owners and Faroese society. I look forward to becoming part of LÍV and – together with the board, management and employees – strengthening operations and building an even stronger and more future-proof company. This is a task that I will undertake with respect, a strong sense of responsibility and enthusiasm,” says Rune Nørregaard.

    For more information:

    +298 530724 — Árni H. Ellefsen
    +45 54303357 — Rune Nørregaard

  • LÍV withdraws from Globe Tracker

    LÍV withdraws from Globe Tracker

    A severance agreement has also been reached with the CEO of the LÍV Group, and the process of finding a new CEO is now underway.

    The LÍV Group has decided to withdraw from the company Globe Tracker ApS. The company has been in serious financial difficulty in recent years, and efforts to strengthen its market position have unfortunately not achieved satisfactory results, according to the LÍV Group.

    Globe Tracker develops tracking equipment and software for monitoring, supervision, and management of shipping containers.

    Although Globe Tracker’s systems have advantages over other similar solutions on the market, the company has struggled financially and has recorded losses for several years. Technical challenges have significantly affected both sales and customer confidence.

    The LÍV Group has therefore decided not to invest any more money in the company.

    Updated Investment Policy

    The LÍV Group made its first investment in Globe Tracker in 2013. P/F Tryggingarfelagið LÍV has invested a total of 84.9 million DKK in the company, while P/F LÍV Lívs- og pensjónstryggingarfelag has invested 89 million DKK.

    The LÍV Group has updated its investment policy, which now specifies that the company will no longer invest in projects of the same investment category as Globe Tracker. The LÍV Group has no other similar investments.

    The total investment portfolio of Tryggingarfelagið LÍV amounts to just under DKK 5 billion. When the collaboration with Globe Tracker ended, the investment was carried on the books at DKK 29.9 million, corresponding to 0.61% of the total investment assets.

    The company regrets the loss of these funds on behalf of its policyholders and acknowledges that this investment did not succeed.

    Severance Agreement

    At the same time as the decision was made not to provide any further funding to Globe Tracker, a severance agreement was reached with the CEO of the LÍV Group, Jan Jakobsen.

    “During the 14 years that Jan Jakobsen has served as CEO of the LÍV Group, he has made a significant contribution, and we are very grateful for his excellent work. The time has now come for a new CEO to lead the LÍV Group forward,” says Árni Ellefsen, Chairman of the Board of P/F Tryggingarfelagið LÍV.

    The process of recruiting a new CEO will begin shortly, and the position will be advertised publicly. Jan Jakobsen has agreed to continue serving as CEO until a successor has been appointed.

  • Market update for mars 2026

    Market update for mars 2026

    What has happened in March and up to mid-April?
    While global equities fell by a full 5% in March, all of this decline—and more—was recovered in the first weeks of April, so global equities are now up by just over 2.5% so far this year.

    While energy and defensive stocks performed best during the downturn in March and cyclical and technology stocks performed worst, the roles have reversed in April.

    Short-term interest rates have risen significantly this year and long-term rates somewhat less, and therefore both short- and long-term bonds have delivered negative returns of around -1% so far this year. Corporate and high-yield bonds have followed the ups and downs of the equity markets since year-end and are now at a total return of around 0%.

    Energy prices rose sharply in March, while many metal prices—including gold—first fell and then increased again.

    Why? The war in Iran is completely driving the markets—for now
    News flow about developments in the war between the US/Israel and Iran, changes in oil prices, and risk assessments related to stagflation have completely driven all movements in global financial markets.

    In the coming weeks, investors will likely also look more closely at company earnings reports from around the world, which show how financial performance has been in the first three months of the year. This could also affect prices in both directions.

    Three scenarios for the war in Iran – investors lean toward the positive ones
    Many financial institutions work with different—typically three—scenarios for how the war in Iran may develop. These vary somewhat between institutions but are roughly as follows:

    1: Gradual de-escalation, quick recovery
    The ceasefire becomes a frozen step toward gradual de-escalation. Shipping through the Strait of Hormuz returns to normal within a month, oil prices stabilize at $80–90, stock markets—and especially price-sensitive stocks—rise, interest rates fall and the euro strengthens, but nervousness remains due to fear that the conflict could escalate again.

    2: Continued restrictions, gradual improvement
    It takes several months before shipping normalizes, and Iran continues to control the Strait of Hormuz, so uncertainty remains high. Oil prices stay around $110–120, central banks cannot cut interest rates. Stocks may rise, but only modestly and with considerable volatility, led by high-quality stocks.

    3: Continued conflict and closure of the strait
    The conflict continues, the strait remains closed for several more months, oil prices surge to $150–180 and significantly weaken global growth. The focus of economic policy shifts from fighting inflation to supporting growth and employment. Central banks cut rates significantly, and investors move toward recession-oriented investments such as energy and defensive stocks, safe bonds, and USD and CHF.

    The positive trend in markets indicates that global investors still expect scenario 1, and that we have therefore likely already seen the worst price declines in this cycle.

  • Market update for february 2026

    Market update for february 2026

    What happened in February?

    Global equities rose by 2.1% in February, but with significant volatility. Many stocks saw daily price swings of 5–10%, which is unusual. The shift away from the U.S. and technology stocks continued, but reversed again in early March, which has also led to noticeable declines in stock prices. After several strong months, Danish equities fell as much as 9% in February—primarily due to Novo.

    Interest rates declined somewhat in February, resulting in fairly good returns across all types of bonds. However, in early March, rates have risen slightly again, and the dollar has strengthened after a weaker period. Oil prices continue to rise, while prices for precious and industrial metals have fallen again, though they remain highly volatile at elevated levels. Cryptocurrencies continue to decline.

    Why? Tech uncertainty and war in the Middle East, and risk of economic stagnation

    Initially, massive artificial intelligence investments by tech companies made an impact on the markets. Investors are concerned about whether these large investments will be profitable. If not, some of the world’s largest companies could face difficulties.

    At present, however, markets are largely driven by developments in the conflict between the U.S./Israel and Iran—particularly the impact on oil prices and the risk of economic stagnation occurring alongside rising inflation.

    Geopolitical instability also tends to hit markets with heavy speculation and high levels of leveraged investments. When these are affected by falling prices, it can trigger forced selling of other assets to cover losses, which in turn can lead to further declines. The largest stock market drops have been seen in Asia and Europe, which are more dependent on imported energy than the U.S., which is self-sufficient. Many stable, so-called defensive stocks in sectors like food and beverages, healthcare, and utilities have performed best during the turbulence.

    The situation in the Middle East and its impact on financial markets

    Financial markets are primarily focused on how the conflict may affect global energy prices, but also indirectly fertilizer and food prices. A large share of raw materials is extracted in the region and must pass through the Strait of Hormuz. It is estimated that 20% of global oil production and up to 40% of key raw materials for fertilizers are transported through this critical passage.

    Most geopolitical experts and financial institutions expect the conflict to be short-lived, with limited and temporary effects on oil and gas prices, equities, and interest rates.

    However, if the conflict drags on or significantly impacts key energy infrastructure—limiting the supply of oil or liquefied natural gas (LNG)—oil prices could quickly rise to $100–120 per barrel. In that case, we could be facing a serious economic shock—similar to the downturn following Russia’s invasion of Ukraine in 2022 or the oil crises of the 1970s. This would mean a negative shock that reduces consumers’ purchasing power, slows economic growth, and increases inflation.

    Such a scenario would be negative for both equities and bonds and would particularly impact many countries in Europe and Asia, while oil-producing nations such as Norway, Brazil, and Russia would benefit. That is why all attention is currently focused on developments in the Middle East, especially what happens to oil prices.

  • Market update for august 2025

    Market update for august 2025

    A Peaceful August with Small, Positive Returns

    In August, market movements were very small — both in the stock, bond, and currency markets, as well as in commodity prices. In the bond markets, yield curves became even steeper, meaning the difference between short-term and long-term interest rates increased.
    Short-term rates remained stable, while long-term rates rose slightly. This led to a slight increase in the value of short-term bonds, while long-term bonds saw small negative returns in August. We’ve seen the same trend for much of the year, and as a result, short-term bonds have yielded a return of 1.8% over the past year, while long-term bonds have produced a negative return of -1.3% over the same period.

    When it comes to riskier bonds, investors continued buying both high-yield bonds and corporate bonds in August, which are currently trading at historically low spreads compared to government bonds. This provided good returns — especially high-yield bonds, which returned 1.3% in August and 6.9% over the past year.

    Global stocks returned 0.2% in August, bringing their return over the past year to 1.2%. Stocks from emerging markets — especially in China and Brazil — increased more than 10%. Danish, and particularly Nordic, stocks also performed well last month, but the Danish market has dropped more than 4% since New Year’s — mainly due to Novo’s decline.

    The dollar remained stable, and prices for gold and silver continued to rise, while pressure on the oil price persists.

    Why? Satisfactory Macroeconomic Data, a Dovish Fed, and Political Uncertainty

    Long-term interest rates have risen in recent months, even as more and more central banks are cutting short-term rates. This is unusual, though it has happened before.

    There are three main reasons for this:

    Many countries have financial difficulties and are currently selling large amounts of government bonds. This is the case in the USA, but also in the UK and France, where political uncertainty is also a factor. Investors are unsure whether politicians will get control over debt and large deficits, and are therefore demanding higher interest rates as a kind of risk premium.

    Another reason is uncertainty surrounding the US Federal Reserve — and its independence. President Trump wants to appoint people to the Fed board who support his desire for lower interest rates. This increases the risk of monetary policy becoming too loose, leading to excessive inflation — which has also increased demand for both gold and silver. Prices are hitting new records daily.

    In early September, the pressure on long-term rates eased a bit, because there are signs of a sudden slowdown in the US labor market. Almost no new jobs are being created at the moment, and unemployment is rising. This gives the Fed an opportunity to cut interest rates multiple times in the coming months — a possibility that both Fed Chair Jay Powell and several board members have mentioned.

    However, the weak labor market data in the US has so far had little impact on investors. That’s evident because stock and high-risk bond prices still appear optimistic. Investors seem to believe that the US economy won’t grind to a sudden halt, but is instead in a balanced state where companies can still earn well, while inflation remains low. Good earnings reports from listed companies reinforce this perception.

    On the other hand, skeptics argue that the labor market signals in the US are classic signs of an upcoming recession — a recession that could also drag the rest of the world into an economic downturn, with falling profits, declining stock prices, and falling interest rates — which would then push bond prices higher.

    The conclusion is, as long as investors believe in a soft economic landing as the macroeconomic scenario, the outlook is good for both stocks and bonds. But rising inflation or declining growth could change that.

  • Milestone days at LÍV

    Milestone days at LÍV

    Today is a special day at LÍV.

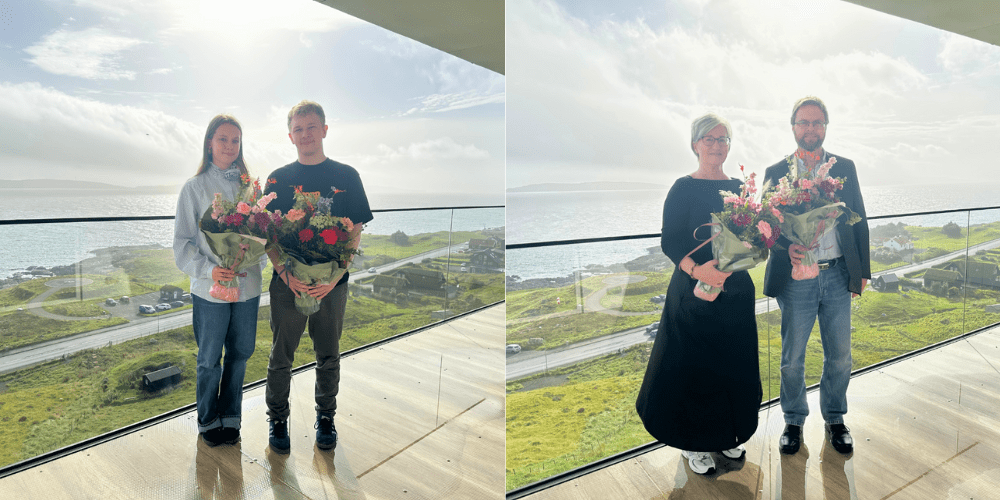
    This morning we had a cozy gathering with Silja, Dánjal, Sunneva, and Óli.

    Our lovely and talented apprentices, Silja and Dánjal, have now completed their training.

    LÍV warmly congratulates Silja and Dánjal on completing their apprenticeships. We are delighted that Silja will continue with us, and at the same time, we wish Dánjal the very best in his future endeavors.

    In addition to this, two of our employees are celebrating work anniversaries.

    Sunneva has worked at LÍV for 40 years, and Óli has worked at LÍV for 10 years.

    We are fortunate and grateful to have such dedicated employees.

    We sincerely congratulate them on their work anniversaries and look forward to many more good years together.

  • Market update for july 2025

    Market update for july 2025

    Stock Market Growth Does Not Reach the Nordic Countries and Denmark – Interest Rates Remain Stable

    The growth in stocks that began in mid-April continued last month, and a strengthened US dollar further boosted returns, resulting in a total return of 4.0% on global equities in July. This also means that the year-to-date return on global stocks has just edged into positive territory. Cyclical or economically sensitive stocks saw the largest gains, while defensive stocks did not rise much.

    Once again, stock market growth did not reach Nordic and Danish equities, which in July had returns of -4.9% and -2.4%, respectively. A notable drop in shares of Novo Nordisk had a particular impact. From the beginning of the year to the end of July, Danish and Nordic equities have declined by about 4%.

    Interest rates continued to fluctuate up and down in July, and the return on Danish government bonds was close to zero as a result. There was renewed interest in high-yield and riskier corporate bonds – over the past year, these have returned between 0.6–1.1% and 2.4–5.5%.

    After several months of decline, the US dollar strengthened in July, which contributed to halting the growth in several commodities such as gold.

    Why? Strong Earnings Reports and Optimism About Growth and Inflation

    The strong returns are primarily due to investors around the world now believing that the global economy will experience a “soft landing” in the second half of 2025 – the so-called “Goldilocks” scenario. This refers to a situation where both growth and inflation are moderately low, so inflation and interest rates remain stable while growth is still strong enough for companies to increase their profits.

    At present, most investors do not believe that Trump’s trade policies will significantly increase inflation in the US. The coming months will show whether this optimism holds. Strong earnings results in the second quarter – especially among American companies and particularly the large tech firms – have also contributed, although the US Federal Reserve’s decision not to cut interest rates had the opposite effect.

    However, profit growth in several sectors has been quite low, which may indicate some growth challenges – both globally and in the US. Lower-than-expected inflation figures, on the other hand, have led many to expect that the US Federal Reserve (Fed) will cut interest rates next year, which has further boosted optimism in the stock market.

    Conclusion, as long as investors continue to believe in a softer global economic outlook, the trend remains positive for both equities and bonds. However, rising inflation or lower growth could impact the current positive trend.

  • LÍV is moving to Óðinshædd

    LÍV is moving to Óðinshædd


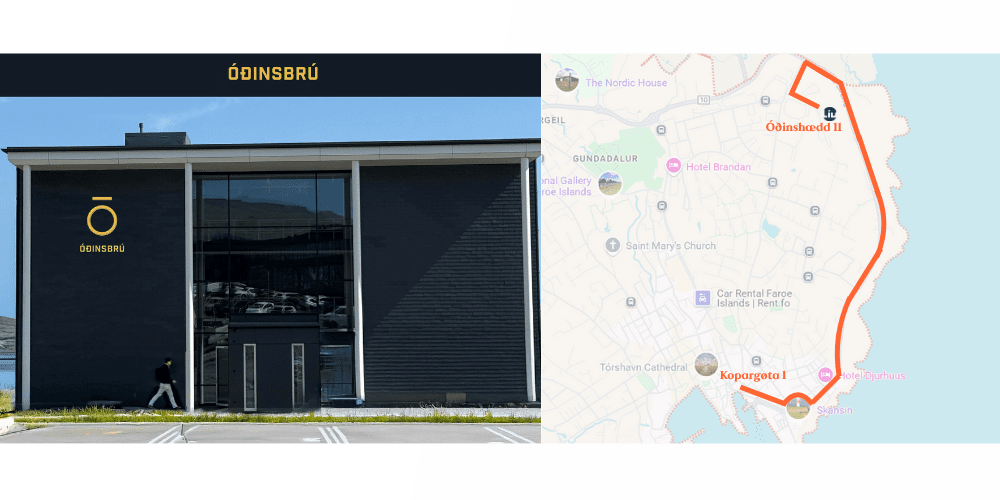
    On July 21, we will be leaving our current premises at Kopargøta 1, where we have been located for many good years. It is with mixed emotions, both gratitude and excitement, that we move on to a new chapter.
    We will be closed for summer holidays from monday, july 21 to friday, august 1

    We will open on August 4 in our new premises at Óðinshædd 11.
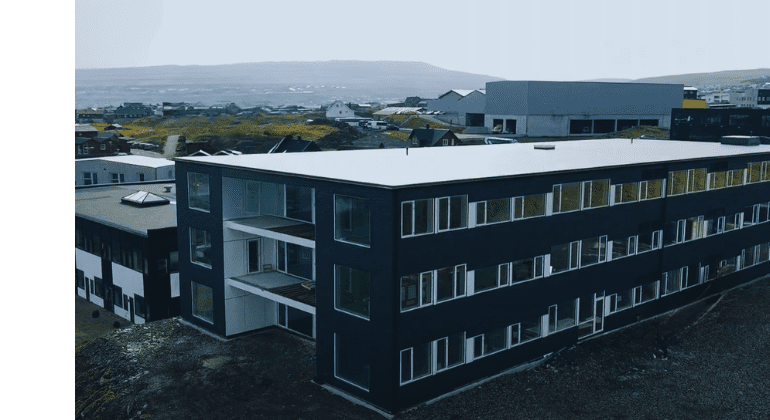
    You will find us on the 3rd floor of Óðinsbrú.

    We look forward to continuing to provide you with excellent service in our new and modern facilities.

  • This is the name of the new building on Óðinshædd

    This is the name of the new building on Óðinshædd

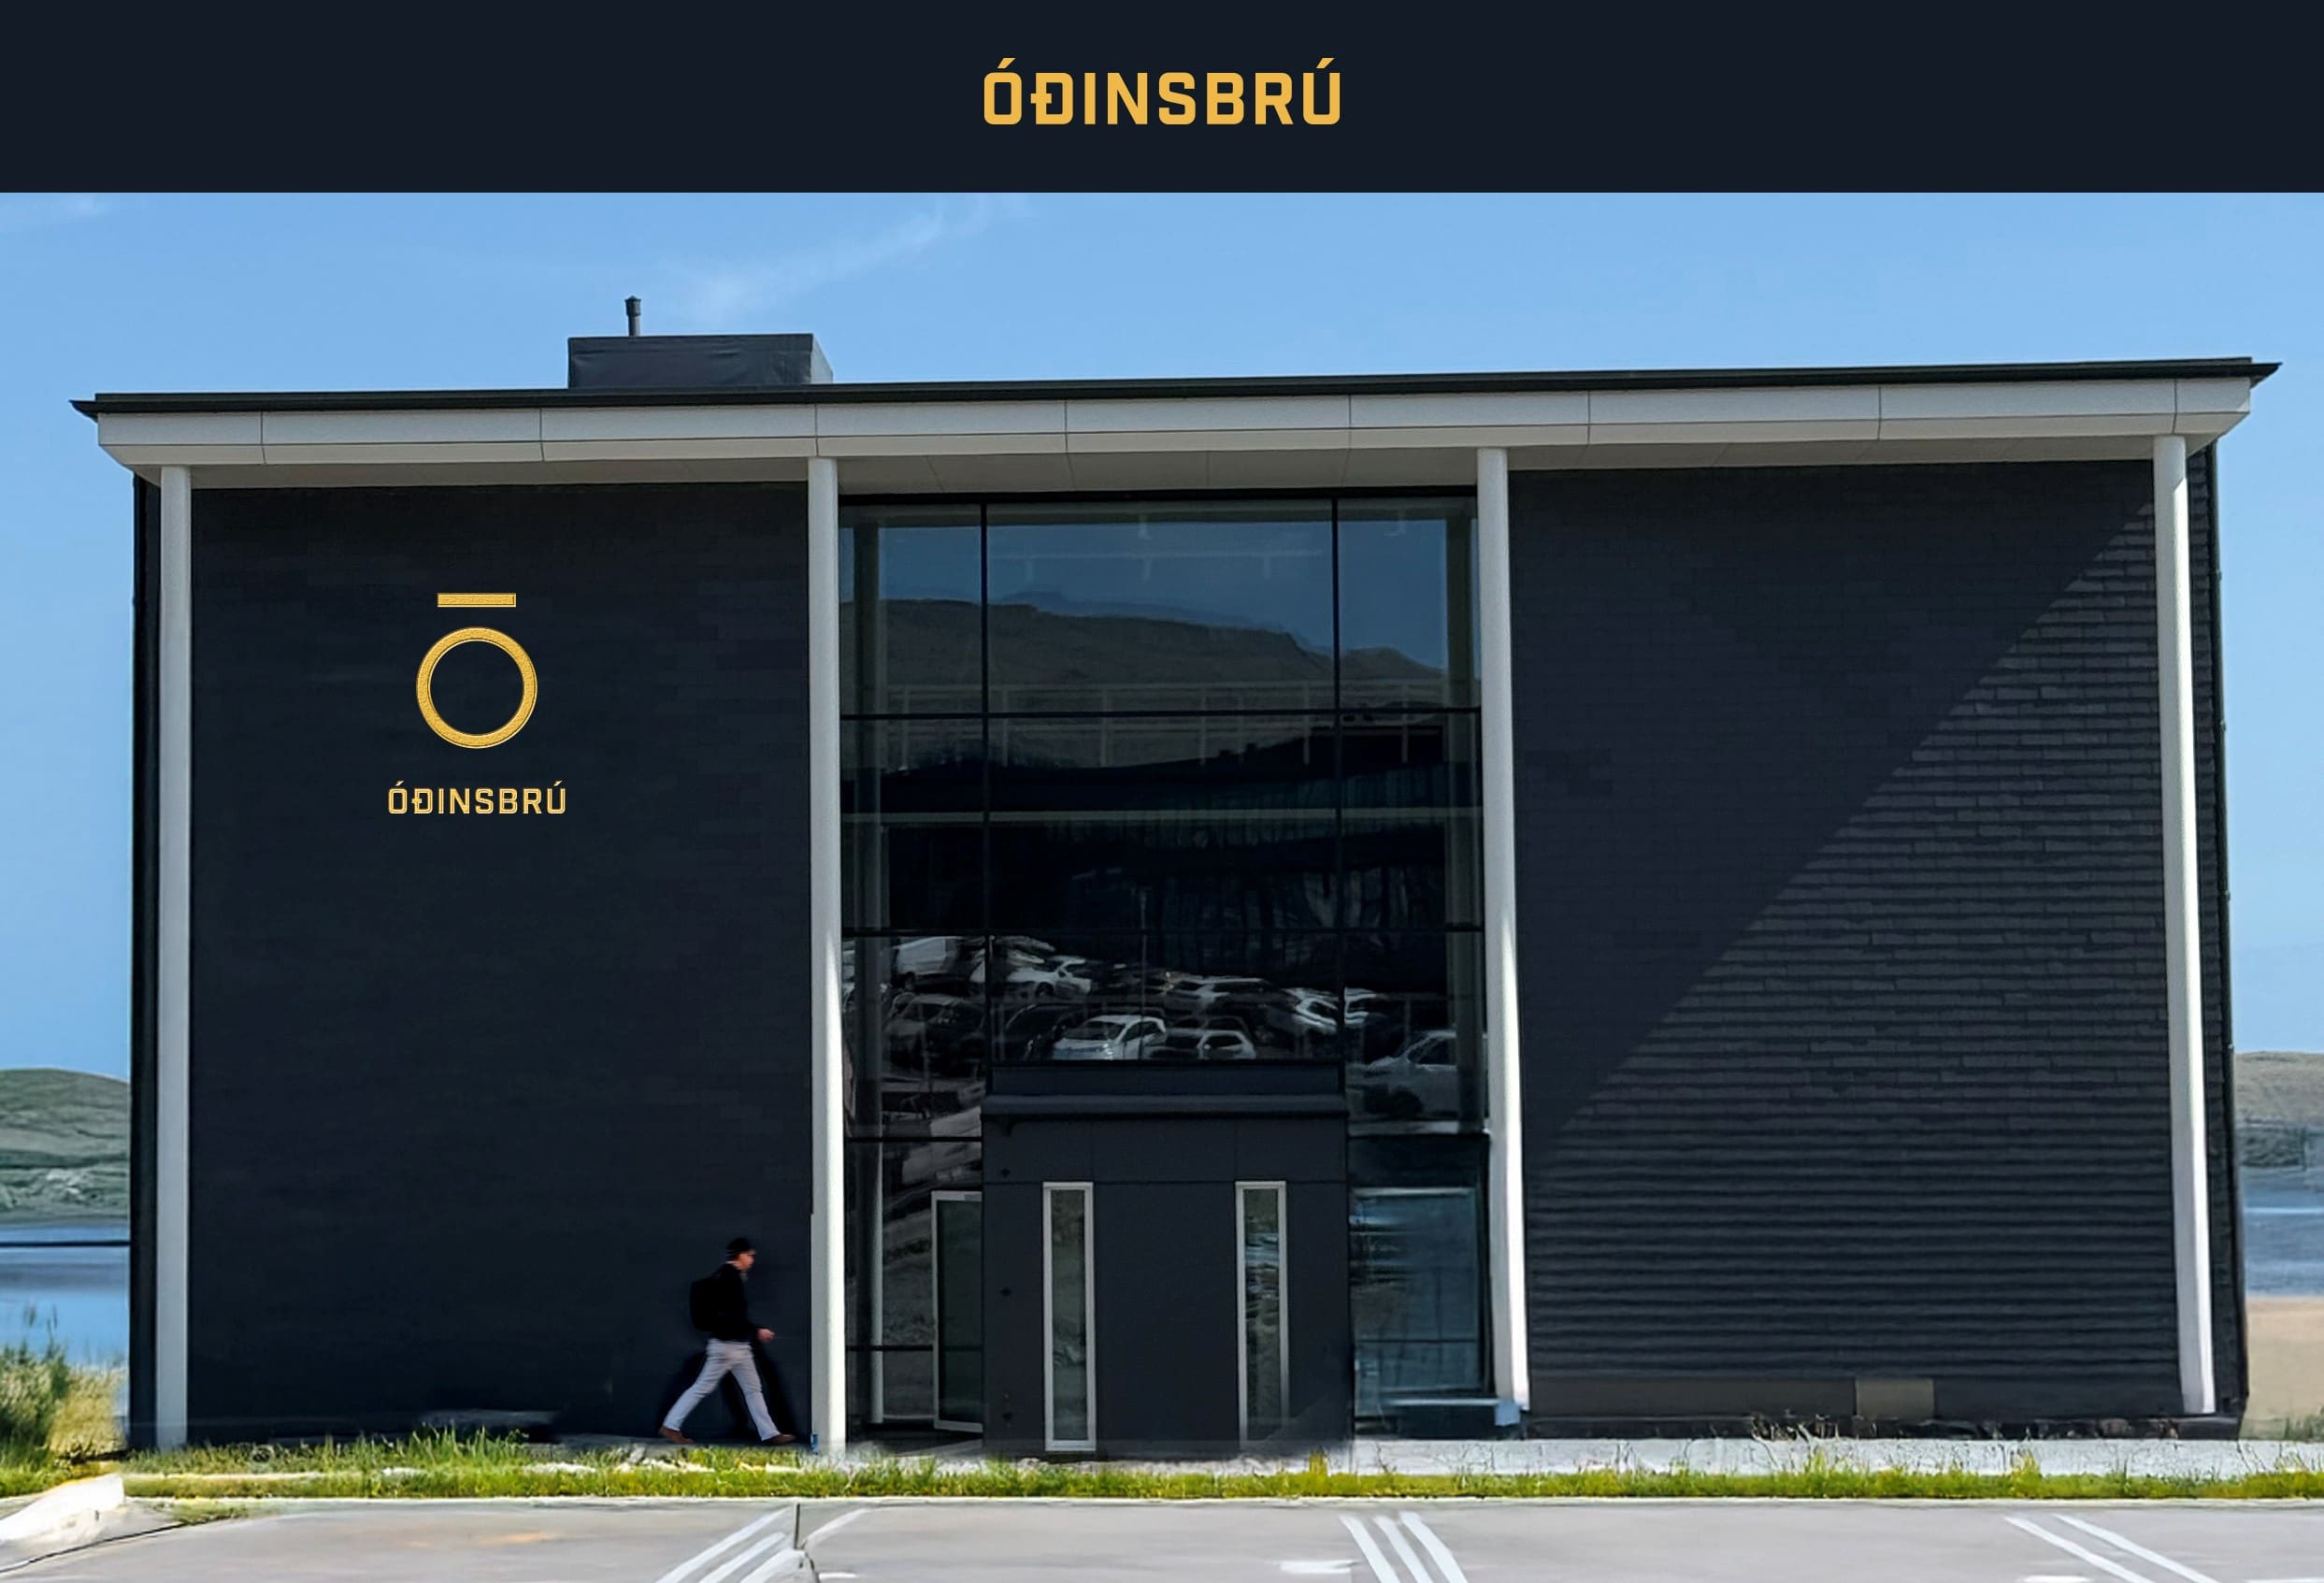
    Today, the insurance company LÍV is announcing the new name and logo of the new building at Óðinshædd. Earlier this year, the company launched a naming and branding contest. After reviewing well over a hundred suggestions, the judging panel has now reached agreement on a new name and logo.

    52 people participated in the competition, and over a hundred suggestions were submitted. Norse mythology — especially the god Óðinn — was a recurring theme among many of the proposals.

    We are overwhelmed by the great interest and want to thank everyone who took the time to send us their suggestions,” says Angela Lindenskov á Bøgarði, marketing coordinator at LÍV.

    The Name

    Although many of the name suggestions were good, none were quite precise enough. The judges had the authority to choose from the pool as they pleased — but they also had the option to select none. Nevertheless, they were inspired by the many great proposals, and from that, a new name emerged.

    “The name is Óðinsbrú, and it fits well with the location. ‘Brú’ is, of course, an old form of the word for ‘bridge’, and the building stands tall on the hilltop, where it somewhat resembles a ship’s bridge. One can imagine Óðinn standing at the helm, gazing out over Nólsoyarfjørður,” Angela explains.

    The Logo

    While no name was directly chosen from the submissions, the logo competition had a different outcome. Among all the elegant logo ideas, one stood out immediately. In its striking simplicity, the logo felt modern, while the classical color scheme gave it a sense of dignity.

    “As seen in the image, the line above the ‘O’ doesn’t slant but is horizontal. This breaks orthographic rules but opens up new interpretations. While a slanted line suggests tension, a horizontal one symbolizes balance, precision, and security — perfectly reflecting the purpose of the building, where Norðoya Sparikassi and we at LÍV will soon be located,” Angela notes.

    Henry á Fríðriksmørk won the logo competition and says the following about the design:

    “Viewed purely as shapes, the logo is simply a circle and a line. Some might think of binary data (zeros and ones), others may see a golden crown and think of money. Perhaps someone even sees a hint of something sacred — like a halo or a royal crown. I wanted the logo to be open to interpretation.”

    The logo will become part of the visual identity of the new building, which will be named Óðinsbrú. And it must be said, the name and logo complement each other well, as together they represent leadership, vision, and security — the very key values of LÍV and Norðoya Sparikassi, who work with life insurance and manage others’ finances.

    “We’ve already grown used to the new name and logo, so now we’re just looking forward to moving in on August 4,” concludes Angela Lindenskov á Bøgarði, marketing coordinator at LÍV.